1031 Exchange Tax Strategy · Nationwide

You are about to sell a property you have owned for decades.

The tax on that sale is the largest single check you may ever write.

A 1031 exchange can defer all of it. Done incorrectly, it defers none of it — and you find out at filing, months after the money is gone.
Licensed Enrolled Agent · Federally credentialed · All fifty states
The problem

The Number Nobody Runs

Most exchanges are structured by people who are not looking at your tax return. The broker is selling the property. The attorney is drafting documents. The qualified intermediary is a custodian holding funds and is not permitted to advise you. Every one of them is doing their job correctly, and not one of them is calculating what you owe if the exchange comes up short.

That calculation is the entire point of the transaction.

What actually creates the tax bill

Five ways a “successful” exchange still generates tax

Cash boot

Proceeds you take out rather than reinvest.

Mortgage boot

Replacement debt lower than the mortgage debt paid off on the property you sold.

Depreciation recapture

Taxed at 25%, and frequently the largest component.

Net investment income tax

An additional 3.8%.

State tax

Up to 13.3% in California, with its own separate rules.

These stack. A partial exchange that looks successful can still produce a six-figure liability, and it is entirely predictable before you sign anything.

Where we sit in the transaction

Five points where the number matters

01

Before the sale

We determine whether the property and the ownership structure qualify, establish the debt outstanding on the property being sold, and define what the exchange actually has to accomplish.

02

Before you sign

We model the tax under multiple scenarios and give you the debt and equity targets required for full deferral. You hand those numbers to your broker.

03

During the 45-day window

We are reachable. Identification rules are unforgiving and the deadline does not move.

04

At filing

Form 8824, carryover basis, and continued depreciation on the replacement property, computed correctly.

05

Every year after

Including California’s Form 3840, which must be filed annually until the deferred gain is recognized. Missing it can put the entire deferred gain back on the table.

Who this is for

Large enough that guessing is not acceptable

You are the right fit if you are selling investment or business real estate with substantial appreciation, substantial depreciation taken, or both — and the tax consequence is large enough that guessing is not acceptable.

Credentials

Why an Enrolled Agent

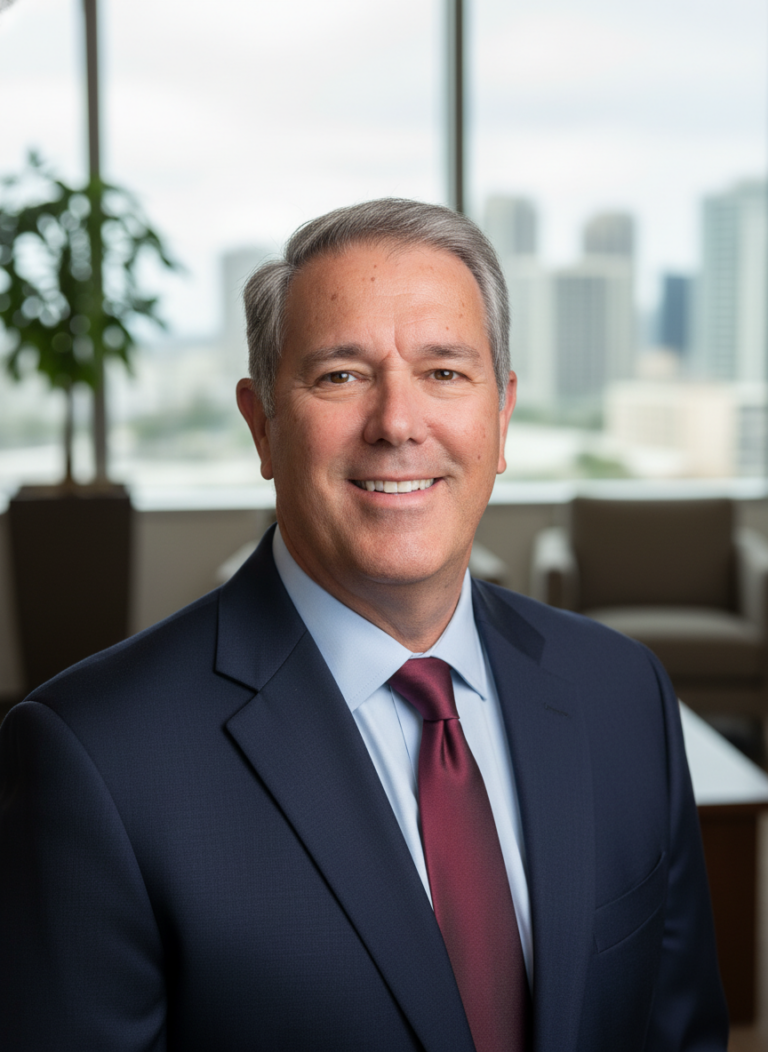
Michael De Luz, Enrolled Agent and founder of 1031 ROADMAP

Michael De Luz, MBA, MA, EA
Founder, 1031 ROADMAP™

An Enrolled Agent is credentialed directly by the U.S. Department of the Treasury and authorized to represent taxpayers before the Internal Revenue Service in all fifty states. It is the only federally licensed tax practitioner designation.

Michael De Luz has practiced in tax and finance for three decades. Exchange work is not a seasonal add-on here — it is the practice.

Next step

Start With the Number

Before you list, before you sign, before the clock starts — find out what is actually at stake.

or call (888) 791-1031

This is general information only, not tax advice. Consult a qualified tax professional — including an Enrolled Agent — for guidance specific to your situation. Read the full disclaimer.